The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.
First, it shows how well a business is managing its budget. Based on the resulting figure of the CAC Payback Period, the shorter the time required to break even on its customer acquisition costs, the more efficient a company is with its sales and marketing expenses. If, however, the result is high, this signals the company is doing something wrong and needs to analyze its current approach.
Running this analysis can also identify a company’s financial perils. The more prolonged the CAC Payback Period, the more likely a company might be facing cash flow concerns. Whether it is caused by overall economic conditions or industry or company-specific challenges, this is another reason for a company to run the numbers to see how it can mitigate or turn around the costs associated with acquiring customers.
The calculation also can help a business determine if it is able to expand to new products and markets and scale up existing product lines. The shorter the time needed to acquire new customers, the more likely a business can grow.
When investors and lenders analyze a company’s financials, including this metric, the more efficient a company is, and the more likely it will attract investors or have lenders offer favorable financing terms.
How to Calculate the CAC Payback Period
This scenario looks at $300,000 in customer acquisition costs, such as marketing, sales, etc., for a three-month period. The company obtained 1,000 new customers and is expected to gain $200,000 in new monthly recurring revenue (MRR), with an estimated gross margin of 60 percent.
First Step: Calculate the CAC by dividing Sales and Marketing Expenses by the new customers (1,000). It’s expressed as follows:
CAC = Sales and Marketing Expenses/Number of New Customers
CAC = $300,000/1,000 = $300 per customer
Second Step: This is to determine the monthly recurring revenue (MRR) per customer. The new MRR amount is divided by the number of newly acquired customers. It’s calculated as follows:
MRR = $200,000/1,000 = $200 per customer
Third Step: Determine the gross margin or how much remains from revenue after subtracting direct costs. In this case, we’ll use 60 percent.
Fourth (and Final) Step: This step determines how many months it will take to recoup the customer acquisition costs from the profits generated by the newly acquired customer. It’s calculated as follows:
CAC Payback Period = $300/($200 x 0.60) = 2.5
Based on the resulting 2.5 figure, it takes, on average, 2.5 months of profit from the newly acquired customers to pay for the customer’s acquisition cost.
Understanding CAC Payback Period Efficiency
If it’s less than 12 months, it’s favorable. This implies a business has an efficient approach to profitability and growth. However, it’s not a hard and fast rule because the repayment time frame can fluctuate based on the economy and the business operations. If a company is a low-margin business or industry (e-commerce, groceries, etc.), a far tighter payback time frame would be necessary to be viable.
There are many factors that can affect this company-specific measurement, such as the industry or sector, current economic conditions, or the business’ approach to gaining new customers. If a company has a shorter CAC Payback Period in an industry that has a generally accepted longer one, this can imply that the company is more efficient in its operations.
This metric is another tool in a financial analyst’s toolbox that can measure and identify efficiency (or lack thereof) and help put businesses back on track for greater financial health.
Calculating the CAC Payback Period
January 1, 2025 · Blog, General Business News, Uncategorized
⏱ 4 min read
The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.
First, it shows how well a business is managing its budget. Based on the resulting figure of the CAC Payback Period, the shorter the time required to break even on its customer acquisition costs, the more efficient a company is with its sales and marketing expenses. If, however, the result is high, this signals the company is doing something wrong and needs to analyze its current approach.
Running this analysis can also identify a company’s financial perils. The more prolonged the CAC Payback Period, the more likely a company might be facing cash flow concerns. Whether it is caused by overall economic conditions or industry or company-specific challenges, this is another reason for a company to run the numbers to see how it can mitigate or turn around the costs associated with acquiring customers.
The calculation also can help a business determine if it is able to expand to new products and markets and scale up existing product lines. The shorter the time needed to acquire new customers, the more likely a business can grow.
When investors and lenders analyze a company’s financials, including this metric, the more efficient a company is, and the more likely it will attract investors or have lenders offer favorable financing terms.
How to Calculate the CAC Payback Period
This scenario looks at $300,000 in customer acquisition costs, such as marketing, sales, etc., for a three-month period. The company obtained 1,000 new customers and is expected to gain $200,000 in new monthly recurring revenue (MRR), with an estimated gross margin of 60 percent.
First Step: Calculate the CAC by dividing Sales and Marketing Expenses by the new customers (1,000). It’s expressed as follows:
CAC = Sales and Marketing Expenses/Number of New Customers
CAC = $300,000/1,000 = $300 per customer
Second Step: This is to determine the monthly recurring revenue (MRR) per customer. The new MRR amount is divided by the number of newly acquired customers. It’s calculated as follows:
MRR = $200,000/1,000 = $200 per customer
Third Step: Determine the gross margin or how much remains from revenue after subtracting direct costs. In this case, we’ll use 60 percent.
Fourth (and Final) Step: This step determines how many months it will take to recoup the customer acquisition costs from the profits generated by the newly acquired customer. It’s calculated as follows:
CAC Payback Period = $300/($200 x 0.60) = 2.5
Based on the resulting 2.5 figure, it takes, on average, 2.5 months of profit from the newly acquired customers to pay for the customer’s acquisition cost.
Understanding CAC Payback Period Efficiency
If it’s less than 12 months, it’s favorable. This implies a business has an efficient approach to profitability and growth. However, it’s not a hard and fast rule because the repayment time frame can fluctuate based on the economy and the business operations. If a company is a low-margin business or industry (e-commerce, groceries, etc.), a far tighter payback time frame would be necessary to be viable.
There are many factors that can affect this company-specific measurement, such as the industry or sector, current economic conditions, or the business’ approach to gaining new customers. If a company has a shorter CAC Payback Period in an industry that has a generally accepted longer one, this can imply that the company is more efficient in its operations.
This metric is another tool in a financial analyst’s toolbox that can measure and identify efficiency (or lack thereof) and help put businesses back on track for greater financial health.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Securing Client Data: The Importance of Encrypted Apps
January 1, 2025 · Blog, Uncategorized, What's New in Technology
⏱ 4 min read
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
Create a Budget
This one never gets old. Why? It’s one of the keys to successful budgeting. You can set up a budget for the year that includes essentials, entertainment, and nice-to-haves, aka your Wish Farm. Then place it in your planner or app – there are many good ones out there. In fact, there’s a TikTok trend called loud budgeting, where people openly discuss their financial goals on social media – why they do or don’t want to buy something. If this is your thing and it helps you stay on track, go for it! If not, a good old-fashioned planner works just as well.
Bucket Your Money
This is the next step after the aforementioned. Split your money into categories: food, rent/ mortgage, utilities, medical, entertainment, vacation, etc. Apps can help you parse out these groups. You might also set up separate banking accounts for some of the necessities so you’ll know to leave them alone and not dip into them, tempting as it may be.
Set Up Auto-Drafts
Let’s say you’re saving for your child’s college fund or a down payment on a car. When you create an auto-draft for a certain amount, you’ll never miss that deposit. If you need to tweak the amount during the year, do it. Here’s the bottom line: 1) You’ll learn to live on less, and 2) you’ll be on the way to making your dreams come true.
Look for Savings Deals
Don’t just settle for the interest rate your current bank is offering. There are many options out there to grow your money. But first, do you want to lock into a fixed rate? This can be useful for long-term goals, such as buying a property. Or do you want an easy-to-access account with the ability to withdraw cash for emergencies or short-term needs like birthday or wedding gifts? Shop around.
Cancel Seldom-Used Subscriptions
Scour your bank statement. Do you need all those online magazine subscriptions? How about newsletters you pay for – the ones you rarely read? Purge your subscriptions, then see how much you’ll save. If you’re so inclined, you could put these dollars toward a gym membership. January is when all the specials appear: zero joining fees, if not a seriously cut rate.
Start a Savings Challenge
Try putting away a small amount every month. Get in the habit of emptying your pockets or coin purse. Safeguard your coins in a mason jar, and then transfer them monthly into your savings account. The next month, increase how much you contribute. Pennies, nickels, dimes, and quarters add up! After a year, you might be surprised how much you’ve saved.
Decide on Goals
These can be small or large. It’s up to you. Spend some time thinking about what’s important. Do you want to remodel your house? Contribute to a beloved charity or cause? One resource you might want to consider setting up is an emergency spending pot. This is essential and sometimes overlooked. Regardless of what you decide, figure out your parameters: how much to set aside, how often, and by when. Having financial targets gives you something to look forward to. Best of all, when you achieve your goal, it’s an awesome feeling.
More often than not, New Year’s resolutions center on getting physically fit. But if you stay the course with your finances, you’ll most definitely be, wait for it … fiscally fit!
Sources
10 things you can do right now to start 2025 with fresh finances
January 1, 2025 · Blog, Tip of the Month, Uncategorized
⏱ 4 min read
Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
Create a Budget
This one never gets old. Why? It’s one of the keys to successful budgeting. You can set up a budget for the year that includes essentials, entertainment, and nice-to-haves, aka your Wish Farm. Then place it in your planner or app – there are many good ones out there. In fact, there’s a TikTok trend called loud budgeting, where people openly discuss their financial goals on social media – why they do or don’t want to buy something. If this is your thing and it helps you stay on track, go for it! If not, a good old-fashioned planner works just as well.
Bucket Your Money
This is the next step after the aforementioned. Split your money into categories: food, rent/ mortgage, utilities, medical, entertainment, vacation, etc. Apps can help you parse out these groups. You might also set up separate banking accounts for some of the necessities so you’ll know to leave them alone and not dip into them, tempting as it may be.
Set Up Auto-Drafts
Let’s say you’re saving for your child’s college fund or a down payment on a car. When you create an auto-draft for a certain amount, you’ll never miss that deposit. If you need to tweak the amount during the year, do it. Here’s the bottom line: 1) You’ll learn to live on less, and 2) you’ll be on the way to making your dreams come true.
Look for Savings Deals
Don’t just settle for the interest rate your current bank is offering. There are many options out there to grow your money. But first, do you want to lock into a fixed rate? This can be useful for long-term goals, such as buying a property. Or do you want an easy-to-access account with the ability to withdraw cash for emergencies or short-term needs like birthday or wedding gifts? Shop around.
Cancel Seldom-Used Subscriptions
Scour your bank statement. Do you need all those online magazine subscriptions? How about newsletters you pay for – the ones you rarely read? Purge your subscriptions, then see how much you’ll save. If you’re so inclined, you could put these dollars toward a gym membership. January is when all the specials appear: zero joining fees, if not a seriously cut rate.
Start a Savings Challenge
Try putting away a small amount every month. Get in the habit of emptying your pockets or coin purse. Safeguard your coins in a mason jar, and then transfer them monthly into your savings account. The next month, increase how much you contribute. Pennies, nickels, dimes, and quarters add up! After a year, you might be surprised how much you’ve saved.
Decide on Goals
These can be small or large. It’s up to you. Spend some time thinking about what’s important. Do you want to remodel your house? Contribute to a beloved charity or cause? One resource you might want to consider setting up is an emergency spending pot. This is essential and sometimes overlooked. Regardless of what you decide, figure out your parameters: how much to set aside, how often, and by when. Having financial targets gives you something to look forward to. Best of all, when you achieve your goal, it’s an awesome feeling.
More often than not, New Year’s resolutions center on getting physically fit. But if you stay the course with your finances, you’ll most definitely be, wait for it … fiscally fit!
Sources
10 things you can do right now to start 2025 with fresh finances
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
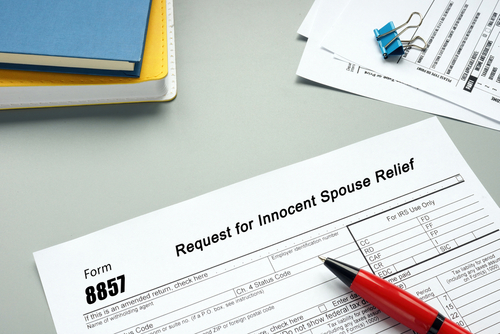
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
What is Innocent Spouse Relief?
January 1, 2025 · Blog, Tax and Financial News, Uncategorized
⏱ 4 min read
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government Spending
December 1, 2024 · Blog, Congress at Work, Uncategorized
⏱ 3 min read
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The coming shakeup of the executive branch, along with Republican control of both houses of Congress, means tax changes are highly likely in 2025 and beyond. Positioning for new and amended tax provisions is already off to the races.
Regardless of the political landscape, on rare occasions, some measures have broad bipartisan support. One such bill is called the Methane Reduction and Economic Growth Act. It proposes adding a new credit for sequestering “qualified” methane from mining activities.
Looking Ahead To 2025
Proponents of the Methane Reduction and Economic Growth Act hope the tax credit will have a beneficial economic impact and create jobs. The idea is to capture and utilize the methane for productive industrial uses or as an alternative for heating buildings. The methane emitted by mines that qualify have long lifespans, with some abandoned mines emitting methane for up to 100 years. The long lifespan of the methane source is hoped to support the significant capital investment required to get the process up and running.
There is also significant potential for job creation in areas most impacted by the shutdown of coal-fired power plants, which in turn devastated the coal mining industry. The concept of using mine methane as an energy source could support rural American jobs.
Landscape and Potential for the Credit
There is a lot of mine methane to capture, with most not currently being captured. The U.S. government estimates abandoned coal mines produce about 237,000 metric tons annually. This methane has many potential uses, including hydrogen production.
Details on the New Subsection
The new section of 45Q credits would be based on the quantity of qualified methane that is sequestered. The captured methane must then be sent to the pipeline and used for producing heat or electricity. To be considered “qualified methane,” it must be captured from certain types of mines, including closed, abandoned, and surface mines. Finally, the methane captured must have otherwise been sent into the atmosphere if it had not been for the capture equipment activity.
Only qualified facilities may obtain the credit. Among other factors, the taxpayer needs to capture a minimum of 2,500 metric tons of methane each year to qualify. There are a lot more technical regulatory requirements related to the specific nature of methane capture, but those are beyond the scope of this article.
Conclusion
Typically, tax bills are split down the aisle based on political partisanship. This makes the passage of tax legislation difficult at best due to competing interests and a divided government. The tax credits related to methane capture, however, appear to be unusually bipartisan in nature. This is due to the unique intersection of democratic support from an environmental and climate perspective, meeting with Republican interest to support economic development in rural coal mining areas where the industry has been devastated. Put these two interests together, and you have the makings for a widely supported bipartisan bill that is very likely to pass.
Energy Tax Credit Changes For 2025
December 1, 2024 · Blog, Guest Article of the Month, Uncategorized
⏱ 3 min read
The coming shakeup of the executive branch, along with Republican control of both houses of Congress, means tax changes are highly likely in 2025 and beyond. Positioning for new and amended tax provisions is already off to the races.
Regardless of the political landscape, on rare occasions, some measures have broad bipartisan support. One such bill is called the Methane Reduction and Economic Growth Act. It proposes adding a new credit for sequestering “qualified” methane from mining activities.
Looking Ahead To 2025
Proponents of the Methane Reduction and Economic Growth Act hope the tax credit will have a beneficial economic impact and create jobs. The idea is to capture and utilize the methane for productive industrial uses or as an alternative for heating buildings. The methane emitted by mines that qualify have long lifespans, with some abandoned mines emitting methane for up to 100 years. The long lifespan of the methane source is hoped to support the significant capital investment required to get the process up and running.
There is also significant potential for job creation in areas most impacted by the shutdown of coal-fired power plants, which in turn devastated the coal mining industry. The concept of using mine methane as an energy source could support rural American jobs.
Landscape and Potential for the Credit
There is a lot of mine methane to capture, with most not currently being captured. The U.S. government estimates abandoned coal mines produce about 237,000 metric tons annually. This methane has many potential uses, including hydrogen production.
Details on the New Subsection
The new section of 45Q credits would be based on the quantity of qualified methane that is sequestered. The captured methane must then be sent to the pipeline and used for producing heat or electricity. To be considered “qualified methane,” it must be captured from certain types of mines, including closed, abandoned, and surface mines. Finally, the methane captured must have otherwise been sent into the atmosphere if it had not been for the capture equipment activity.
Only qualified facilities may obtain the credit. Among other factors, the taxpayer needs to capture a minimum of 2,500 metric tons of methane each year to qualify. There are a lot more technical regulatory requirements related to the specific nature of methane capture, but those are beyond the scope of this article.
Conclusion
Typically, tax bills are split down the aisle based on political partisanship. This makes the passage of tax legislation difficult at best due to competing interests and a divided government. The tax credits related to methane capture, however, appear to be unusually bipartisan in nature. This is due to the unique intersection of democratic support from an environmental and climate perspective, meeting with Republican interest to support economic development in rural coal mining areas where the industry has been devastated. Put these two interests together, and you have the makings for a widely supported bipartisan bill that is very likely to pass.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Understanding Carbon Accounting
December 1, 2024 · Accounting News, Blog, Uncategorized
⏱ 3 min read
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.



 The
 Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
 The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
 All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
 The coming shakeup of the executive branch, along with Republican control of both houses of Congress, means tax changes are highly likely in 2025 and beyond. Positioning for new and amended tax provisions is already off to the races.
 Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.