When it comes to business operations and measuring performance, the optimal production scale a company can sustain is an important metric to measure. If a business’ capacity can’t be realized and sustained – or the bottlenecks can’t be identified and addressed in a timely manner – a business will likely stagnate and fail. Understanding more about capacity management can help businesses reduce the chances of dealing with sub-optimal performance.
Capacity Defined
A business’ capacity is defined as its highest level of production on a consistent basis. By measuring the capacity of a business, we can calculate its ongoing revenue projections. This type of evaluation also can help a company determine how to manage production snarls and identify ways to increase capacity reserves to help it manage abnormally high production demands.
Capacity Utilization Rate Defined
This ratio is the percentage of a business’ production capacity that’s currently utilized. If an organization has a capacity utilization rate of 60 percent, the firm is currently operating at 60 percent of its theoretical capacity. When it comes to analyzing a business, this percentage can determine how much capacity may be available for spikes in demand.
This is calculated by taking the actual output and dividing it by theoretical output, with the result multiplied by 100, or as follows:
(actual output/theoretical output) x 100 = capacity utilization rate
Activity Capacity Overview
Activity capacity assesses the scale of production of a particular task over a given time frame (a quarter, six months, or a 12-month fiscal year) while accounting for regular production factors. Common facets of production that affect output include worker rest periods, equipment upkeep, crew swaps, etc. This investigation allows a business to determine if it can accomplish projected production in the near term with existing equipment or if the business needs to analyze bottlenecks before reassessing.
Budgeted Capacity
This method is used to approximate the manufacturing quantity scheduled for subsequent time frames. Criteria that’s analyzed for the plan hinges on forecasted market demand, resource availability and production capabilities. It’s an imperative consideration that impacts sales forecasts, indirect operational budgets, and the direct production budget.
Depending on the type of business, budgeted capacity can be represented in either hours or units. For example, a company would evaluate industry and economic demand trends, along with the time frame it’s trying to forecast and what resources the business has available for production. The following steps are commonplace during this process:
Step 1:
The business plans to produce 480,000 widgets for the projected time frame.
Step 2:
The business looks at how many shifts will be run, how much each shift can produce, how many days the company will operate, and the number of hours available for production for each shift. This will help the company determine production and resource availability for the projected time frame.
Step 3:
The business will look at what it’s able to produce based on its full capacity:
Potential per shift = 100 widgets per hour x 8 hours a shift x 1 shift = 800 widgets
Potential per day = 800 widgets per shift x 3 shifts per day = 2,400 widgets
Annual production = 2,400 widgets per day x 275 working days per year = 660,000 widgets
Conclusion
The budgeted production of 480,000 widgets annually is approximately 73 percent of the business’s total production capacity. This leaves the business with ample room to respond to new clients and/or increased demand from existing clients for unexpected orders.
While each business is unique, taking steps to analyze and make more educated projections is one way to increase a company’s efficiency.
Optimizing Your Business’ Performance with Capacity Management
February 1, 2024 · Accounting News, Blog, Uncategorized
⏱ 3 min read
When it comes to business operations and measuring performance, the optimal production scale a company can sustain is an important metric to measure. If a business’ capacity can’t be realized and sustained – or the bottlenecks can’t be identified and addressed in a timely manner – a business will likely stagnate and fail. Understanding more about capacity management can help businesses reduce the chances of dealing with sub-optimal performance.
Capacity Defined
A business’ capacity is defined as its highest level of production on a consistent basis. By measuring the capacity of a business, we can calculate its ongoing revenue projections. This type of evaluation also can help a company determine how to manage production snarls and identify ways to increase capacity reserves to help it manage abnormally high production demands.
Capacity Utilization Rate Defined
This ratio is the percentage of a business’ production capacity that’s currently utilized. If an organization has a capacity utilization rate of 60 percent, the firm is currently operating at 60 percent of its theoretical capacity. When it comes to analyzing a business, this percentage can determine how much capacity may be available for spikes in demand.
This is calculated by taking the actual output and dividing it by theoretical output, with the result multiplied by 100, or as follows:
(actual output/theoretical output) x 100 = capacity utilization rate
Activity Capacity Overview
Activity capacity assesses the scale of production of a particular task over a given time frame (a quarter, six months, or a 12-month fiscal year) while accounting for regular production factors. Common facets of production that affect output include worker rest periods, equipment upkeep, crew swaps, etc. This investigation allows a business to determine if it can accomplish projected production in the near term with existing equipment or if the business needs to analyze bottlenecks before reassessing.
Budgeted Capacity
This method is used to approximate the manufacturing quantity scheduled for subsequent time frames. Criteria that’s analyzed for the plan hinges on forecasted market demand, resource availability and production capabilities. It’s an imperative consideration that impacts sales forecasts, indirect operational budgets, and the direct production budget.
Depending on the type of business, budgeted capacity can be represented in either hours or units. For example, a company would evaluate industry and economic demand trends, along with the time frame it’s trying to forecast and what resources the business has available for production. The following steps are commonplace during this process:
Step 1:
The business plans to produce 480,000 widgets for the projected time frame.
Step 2:
The business looks at how many shifts will be run, how much each shift can produce, how many days the company will operate, and the number of hours available for production for each shift. This will help the company determine production and resource availability for the projected time frame.
Step 3:
The business will look at what it’s able to produce based on its full capacity:
Potential per shift = 100 widgets per hour x 8 hours a shift x 1 shift = 800 widgets
Potential per day = 800 widgets per shift x 3 shifts per day = 2,400 widgets
Annual production = 2,400 widgets per day x 275 working days per year = 660,000 widgets
Conclusion
The budgeted production of 480,000 widgets annually is approximately 73 percent of the business’s total production capacity. This leaves the business with ample room to respond to new clients and/or increased demand from existing clients for unexpected orders.
While each business is unique, taking steps to analyze and make more educated projections is one way to increase a company’s efficiency.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Email marketing remains the most powerful and effective tool, especially for its high ROI, reach, and engagement. It plays a significant role in business growth. However, more stringent measures are necessary due to evolving threats, hence the recent email deliverability requirements.
Starting this February, major email providers Gmail and Yahoo are implementing stricter email deliverability rules to combat spam and protect user inboxes. This announcement was made by both Google and Yahoo on Oct. 3, 2023, indicating a united effort to enhance email security.
Initially intended for bulk senders (marketers, businesses, and individuals) sending more than 5,000 emails a day, it also applies to senders who send regular emails to their subscribers and meet criteria as per the updated Google Email Sender Guidelines.
Although it may sound strict, there is nothing to worry about. By understanding the rules and adopting best practices, you can ensure your messages land safely in your subscribers’ inboxes.
Key Rules to Remember
Domain Authentication is Paramount – Implement security protocols, including Domain Keys Identified Mail (DKIM), Sender Policy Framework (SPF), and Domain-based Message Authentication, Reporting and Conformance (DMARC) to verify your sending domain and prevent spoofing. DKIM digitally signs emails for verification. SPF confirms that sending domain authorization prevents spammers from impersonating and sending messages from your domain, while DMARC specifies the handling of unauthenticated emails. Basically, these protocols confirm your sending domain as legitimate and not from a malicious email spammer or phisher. Although these protocols have been previously considered best practices, many senders have unknowingly or knowingly bypassed them. Some have ignored them, considering them challenging to deploy. Hence, the step to enforce them as mandatory requirements.
One-Click Unsubscribe is Mandatory – Make it easy for subscribers to opt out with a clear and accessible unsubscribe link in every email. The unsubscribe requests must be honored within 2 days. You can add an unsubscribe button to the header, whereby recipients can unsubscribe easily instead of marking an email as spam. This will ensure email deliverability is not harmed. Allowing easy unsubscribe also offers the benefit of having an email list of quality subscribers.
Maintain a Low Spam Complaint Rate – Keep your spam complaints below 0.3 percent (ideally, this should be below 0.1 percent) to avoid landing in the spam folder or getting blacklisted. Failing to comply with the spam complaint threshold could put the sending domain under review, restricting your email reach.
Beyond the Rules: Deliverability Best Practices
Clean and Permission-Based Email Lists – Send only to subscribers who have opted-in, and keep your list clean by removing inactive users and bounced addresses.
Personalization and Segmentation – Tailor your emails to individual preferences and segment your list based on demographics, interests, or engagement levels.
Mobile-Friendly Design – Ensure your emails are optimized for mobile devices, as most users check their email on smartphones.
Subject Line Optimization – Craft compelling and relevant subject lines that invite users to open your emails.
Craft High-Quality and Engaging Content – Provide relevant and valuable information to maintain audience interest and avoid being marked as spam.
Avoid Spammy Tactics – Avoid excessive images, ALL CAPS text, and misleading content.
Engagement and Reputation – Encourage engagement by asking questions, including social media links, and providing valuable content. Positive user interactions improve the sender’s reputation.
Consequences of Ignoring the Rules
Failing to adhere to the new rules can have severe consequences, including:
Emails Landing in Spam Folders – Your messages may never reach your intended audience.
Domain or IP Blacklisting – Repeated violations can lead to your domain or IP address being blocked by email providers.
Decreased Sender Reputation – This can negatively impact your future deliverability rates, affecting domain reputation and overall business performance.
Adapting to the New Landscape
Although these requirements may seem overwhelming, they represent an opportunity to improve your email marketing practices and build stronger relationships with your subscribers. By prioritizing sender authentication, clear communication, and valuable content, you can ensure your emails reach the right inboxes and achieve your marketing goals.
Remember, staying informed about email deliverability best practices and adapting to evolving regulations is crucial for successful email marketing in today’s landscape.
New Email Deliverability Rules: Reaching Gmail and Yahoo Subscribers in 2024
February 1, 2024 · Blog, Uncategorized, What's New in Technology
⏱ 4 min read
Email marketing remains the most powerful and effective tool, especially for its high ROI, reach, and engagement. It plays a significant role in business growth. However, more stringent measures are necessary due to evolving threats, hence the recent email deliverability requirements.
Starting this February, major email providers Gmail and Yahoo are implementing stricter email deliverability rules to combat spam and protect user inboxes. This announcement was made by both Google and Yahoo on Oct. 3, 2023, indicating a united effort to enhance email security.
Initially intended for bulk senders (marketers, businesses, and individuals) sending more than 5,000 emails a day, it also applies to senders who send regular emails to their subscribers and meet criteria as per the updated Google Email Sender Guidelines.
Although it may sound strict, there is nothing to worry about. By understanding the rules and adopting best practices, you can ensure your messages land safely in your subscribers’ inboxes.
Key Rules to Remember
Domain Authentication is Paramount – Implement security protocols, including Domain Keys Identified Mail (DKIM), Sender Policy Framework (SPF), and Domain-based Message Authentication, Reporting and Conformance (DMARC) to verify your sending domain and prevent spoofing. DKIM digitally signs emails for verification. SPF confirms that sending domain authorization prevents spammers from impersonating and sending messages from your domain, while DMARC specifies the handling of unauthenticated emails. Basically, these protocols confirm your sending domain as legitimate and not from a malicious email spammer or phisher. Although these protocols have been previously considered best practices, many senders have unknowingly or knowingly bypassed them. Some have ignored them, considering them challenging to deploy. Hence, the step to enforce them as mandatory requirements.
One-Click Unsubscribe is Mandatory – Make it easy for subscribers to opt out with a clear and accessible unsubscribe link in every email. The unsubscribe requests must be honored within 2 days. You can add an unsubscribe button to the header, whereby recipients can unsubscribe easily instead of marking an email as spam. This will ensure email deliverability is not harmed. Allowing easy unsubscribe also offers the benefit of having an email list of quality subscribers.
Maintain a Low Spam Complaint Rate – Keep your spam complaints below 0.3 percent (ideally, this should be below 0.1 percent) to avoid landing in the spam folder or getting blacklisted. Failing to comply with the spam complaint threshold could put the sending domain under review, restricting your email reach.
Beyond the Rules: Deliverability Best Practices
Clean and Permission-Based Email Lists – Send only to subscribers who have opted-in, and keep your list clean by removing inactive users and bounced addresses.
Personalization and Segmentation – Tailor your emails to individual preferences and segment your list based on demographics, interests, or engagement levels.
Mobile-Friendly Design – Ensure your emails are optimized for mobile devices, as most users check their email on smartphones.
Subject Line Optimization – Craft compelling and relevant subject lines that invite users to open your emails.
Craft High-Quality and Engaging Content – Provide relevant and valuable information to maintain audience interest and avoid being marked as spam.
Avoid Spammy Tactics – Avoid excessive images, ALL CAPS text, and misleading content.
Engagement and Reputation – Encourage engagement by asking questions, including social media links, and providing valuable content. Positive user interactions improve the sender’s reputation.
Consequences of Ignoring the Rules
Failing to adhere to the new rules can have severe consequences, including:
Emails Landing in Spam Folders – Your messages may never reach your intended audience.
Domain or IP Blacklisting – Repeated violations can lead to your domain or IP address being blocked by email providers.
Decreased Sender Reputation – This can negatively impact your future deliverability rates, affecting domain reputation and overall business performance.
Adapting to the New Landscape
Although these requirements may seem overwhelming, they represent an opportunity to improve your email marketing practices and build stronger relationships with your subscribers. By prioritizing sender authentication, clear communication, and valuable content, you can ensure your emails reach the right inboxes and achieve your marketing goals.
Remember, staying informed about email deliverability best practices and adapting to evolving regulations is crucial for successful email marketing in today’s landscape.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Variance analysis is found by determining the difference between what was budgeted and what actually occurred. Additionally, when variances are added together, we get a better picture of how well a company is measuring its performance against expected metrics. It’s also important to be mindful that each metric is measured to determine what the actual cost is versus the industry’s standard cost.
Whether it’s materials, labor, electricity, or another metric, if the actual cost is lower than the standard cost for the same quantity of materials, it would be a favorable price variance. However, if the number of materials was more than the standard quantity, it would be considered an unfavorable variance. Examining variance allows us to analyze the price and quantity of the variable being analyzed. Always keep in mind that unusual or significant variances should be investigated to see why such anomalies exist.
It’s important to distinguish between variances and the types of inputs. When it comes to materials, labor, and similar variable overhead, variances to be analyzed are for price and quantity/efficiency. When it comes to fixed overhead, analysis looks at variances in budget and volume.
One way to conduct variance analysis is through the Column Method. The following example illustrates this:
A business produces widgets. The following assumptions are made:
6,000 widgets are produced in a month
Direct labor hours are used as the basis to allocate overhead costs to products
Denominator level of activity is 8,060 hours, resulting in $48,360 in fixed overhead expenses budgeted.
Other cost assumptions include:
Direct Costs
Labor: 2.6 hours/widget @ $14 per hour
Materials: 10 pieces/widget @ $1/widget
Overhead
Variable: 2.6 hours/widget @ $8/hour
Fixed: 1.3 hours /widget @ $12/hour
However, the business saw the following costs for the month’s production:
Variable overhead manufacturing costs: $34,000
Fixed overhead manufacturing costs: $50,000
Both of the following are Direct Costs:
Material: 50,000 items bought @ $0.96/widget
Labor: 8,000 hours totaling $128,000
Materials Variance
Real Quantity x Real Price = 50,000 pieces x $0.96 per widget = $48,000
Real Quantity x Industry Price = 50,000 pieces x $1 per widget = $50,000
Standard Quantity x Industry Price = 36,000 pieces x $1 per widget = $36,000
Price Variance = $50,000 – $48,000 = $2,000
Quantity Variance = $50,000 – $36,000 = $14,000
When we find the difference between these two amounts, there’s an unfavorable variance of $12,000. Additionally, it’s worth looking at why there were 50,000 pieces used versus the standardized 36,000 pieces. It could be due to defective materials, problematic machinery, etc.
Labor Variance
Real Hours x Real Rate = 8,000 hours x $16 per hour = $128,000
Real Hours x Industry Rate = 8,000 x $14 per hour = $112,000
Standard Hours x Industry Rate = 7,800 x $14 hour = $109,200
Based on this calculation, there’s a total unfavorable variance of -$18,800. Management should look at why labor costs are higher than the standard and why production took more supplies than the industry standard.
While this is not all-encompassing, it does show the importance of understanding the nuances of calculating variances and how it’s essential to understanding a business’ (in)efficiency.
Understanding How Variances Vary
February 1, 2024 · Blog, General Business News, Uncategorized
⏱ 3 min read
Variance analysis is found by determining the difference between what was budgeted and what actually occurred. Additionally, when variances are added together, we get a better picture of how well a company is measuring its performance against expected metrics. It’s also important to be mindful that each metric is measured to determine what the actual cost is versus the industry’s standard cost.
Whether it’s materials, labor, electricity, or another metric, if the actual cost is lower than the standard cost for the same quantity of materials, it would be a favorable price variance. However, if the number of materials was more than the standard quantity, it would be considered an unfavorable variance. Examining variance allows us to analyze the price and quantity of the variable being analyzed. Always keep in mind that unusual or significant variances should be investigated to see why such anomalies exist.
It’s important to distinguish between variances and the types of inputs. When it comes to materials, labor, and similar variable overhead, variances to be analyzed are for price and quantity/efficiency. When it comes to fixed overhead, analysis looks at variances in budget and volume.
One way to conduct variance analysis is through the Column Method. The following example illustrates this:
A business produces widgets. The following assumptions are made:
6,000 widgets are produced in a month
Direct labor hours are used as the basis to allocate overhead costs to products
Denominator level of activity is 8,060 hours, resulting in $48,360 in fixed overhead expenses budgeted.
Other cost assumptions include:
Direct Costs
Labor: 2.6 hours/widget @ $14 per hour
Materials: 10 pieces/widget @ $1/widget
Overhead
Variable: 2.6 hours/widget @ $8/hour
Fixed: 1.3 hours /widget @ $12/hour
However, the business saw the following costs for the month’s production:
Variable overhead manufacturing costs: $34,000
Fixed overhead manufacturing costs: $50,000
Both of the following are Direct Costs:
Material: 50,000 items bought @ $0.96/widget
Labor: 8,000 hours totaling $128,000
Materials Variance
Real Quantity x Real Price = 50,000 pieces x $0.96 per widget = $48,000
Real Quantity x Industry Price = 50,000 pieces x $1 per widget = $50,000
Standard Quantity x Industry Price = 36,000 pieces x $1 per widget = $36,000
Price Variance = $50,000 – $48,000 = $2,000
Quantity Variance = $50,000 – $36,000 = $14,000
When we find the difference between these two amounts, there’s an unfavorable variance of $12,000. Additionally, it’s worth looking at why there were 50,000 pieces used versus the standardized 36,000 pieces. It could be due to defective materials, problematic machinery, etc.
Labor Variance
Real Hours x Real Rate = 8,000 hours x $16 per hour = $128,000
Real Hours x Industry Rate = 8,000 x $14 per hour = $112,000
Standard Hours x Industry Rate = 7,800 x $14 hour = $109,200
Based on this calculation, there’s a total unfavorable variance of -$18,800. Management should look at why labor costs are higher than the standard and why production took more supplies than the industry standard.
While this is not all-encompassing, it does show the importance of understanding the nuances of calculating variances and how it’s essential to understanding a business’ (in)efficiency.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
January has come and gone. You may or may not have stuck to your resolutions, but the good news is that February is here. Now is the perfect time to hunker down and get your monetary ducks in a row. Here are a few things to put on your agenda to get your financial house in order.
Pay Off Holiday Debt
Yes, it was fun to go shopping for holiday gifts, but those interest rates are high – you’ll want to pay your balances off as quickly as possible. And here’s a tip: you can make more than one payment per billing period. In other words, instead of waiting for your next paycheck, pay some of the balance now and some later. This will reduce the interest you’d pay if you waited two more weeks to pay in full. This way, you can actually pay your credit card bills more frequently and pay less over time. While you’re at it, look for lower interest rates and transfer those balances. All it takes is a Google search for “zero balance transfer credit card offers,” and you’ll find what you need in no time.
Start Working on Your Taxes
April will be here before you know it, so getting a jump on taxes is a smart idea. Also, filing early will give you more time to figure out how much you owe, if anything. If you want to take the guesswork out of preparing your taxes, you might consider hiring a tax professional. When you make your selection, ask for a price quote. Some tax preparers often want to see which forms you need before they work on your taxes, but you can still ask for a list of fees for various types of tax help to get a ballpark idea. Here’s a red flag: if someone says they’ll base your fees on a percentage of your refund, run away. This is a violation of IRS rules.
Get a Free Credit Report
All the big reporting companies – Equifax, Experian, and TransUnion – offer a free report one time every 12 months. So why not find out? When you see the truth of your credit report, it can motivate you to change some habits, like paying earlier, more often, and on time. No one likes late fees.
Save on a Gym Membership
In January, you probably got pummeled with lots of solicitations for a gym membership at low, low prices, but in February, the prices are even lower. If you don’t want to commit, you can sign up for a trial run. You can even negotiate a deal if you ask to speak to the manager. Finally, some gyms will offer you a deep discount if you agree to use the facilities during off-peak hours or on certain days. Flexibility is the key!
Buy Things on Deep Discount
With high prices and high-interest rates, it makes sense to check out all the price cuts on Consumer Reports. On this site, you’ll find all the good stuff: cars, home and garden supplies, appliances, electronics, and more.
These are just a few of the items you can put on your financial to-do list. All it takes is carving out some time and getting started. Once you get going, you’ll probably make more progress than you ever dreamed.
February 1, 2024 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
January has come and gone. You may or may not have stuck to your resolutions, but the good news is that February is here. Now is the perfect time to hunker down and get your monetary ducks in a row. Here are a few things to put on your agenda to get your financial house in order.
Pay Off Holiday Debt
Yes, it was fun to go shopping for holiday gifts, but those interest rates are high – you’ll want to pay your balances off as quickly as possible. And here’s a tip: you can make more than one payment per billing period. In other words, instead of waiting for your next paycheck, pay some of the balance now and some later. This will reduce the interest you’d pay if you waited two more weeks to pay in full. This way, you can actually pay your credit card bills more frequently and pay less over time. While you’re at it, look for lower interest rates and transfer those balances. All it takes is a Google search for “zero balance transfer credit card offers,” and you’ll find what you need in no time.
Start Working on Your Taxes
April will be here before you know it, so getting a jump on taxes is a smart idea. Also, filing early will give you more time to figure out how much you owe, if anything. If you want to take the guesswork out of preparing your taxes, you might consider hiring a tax professional. When you make your selection, ask for a price quote. Some tax preparers often want to see which forms you need before they work on your taxes, but you can still ask for a list of fees for various types of tax help to get a ballpark idea. Here’s a red flag: if someone says they’ll base your fees on a percentage of your refund, run away. This is a violation of IRS rules.
Get a Free Credit Report
All the big reporting companies – Equifax, Experian, and TransUnion – offer a free report one time every 12 months. So why not find out? When you see the truth of your credit report, it can motivate you to change some habits, like paying earlier, more often, and on time. No one likes late fees.
Save on a Gym Membership
In January, you probably got pummeled with lots of solicitations for a gym membership at low, low prices, but in February, the prices are even lower. If you don’t want to commit, you can sign up for a trial run. You can even negotiate a deal if you ask to speak to the manager. Finally, some gyms will offer you a deep discount if you agree to use the facilities during off-peak hours or on certain days. Flexibility is the key!
Buy Things on Deep Discount
With high prices and high-interest rates, it makes sense to check out all the price cuts on Consumer Reports. On this site, you’ll find all the good stuff: cars, home and garden supplies, appliances, electronics, and more.
These are just a few of the items you can put on your financial to-do list. All it takes is carving out some time and getting started. Once you get going, you’ll probably make more progress than you ever dreamed.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
For many, buying a home is the biggest asset they will ever own. However, you aren’t able to fully benefit from that asset until you pay off the mortgage; until then, it is technically a liability. The most common length of a mortgage loan is 30 years, but most people either sell their home, refinance their mortgage – or even pay it off before the end of that term.
What are the pros and cons of paying off a mortgage early? Obviously, you no longer have to make monthly payments, so money can be directed elsewhere. It is advisable to pay off your mortgage before you retire when most people live on a lower, fixed income. By having the mortgage paid off, that money can be redirected to other household expenses and/or provide higher discretionary income.
It should be noted that paying off your mortgage doesn’t provide relief from other routine, high-ticket home expenses such as property taxes, homeowners’ insurance, or regular maintenance. However, owning your home outright means it can’t be foreclosed on and taken from you. It also provides a large financial asset from which you can tap the equity or sell for a windfall.
While paying off your mortgage can provide security and peace of mind, you should consider all the factors before going down this path. For example, you may not have enough discretionary income to devote to making extra payments to your mortgage loan principal.
Usually, in the first 10 to 20 years of homeownership, buyers are juggling a multitude of financial obligations – raising a family, building an emergency fund, saving for college, taking annual vacations, and investing for retirement. That doesn’t always leave a lot of money left over for your mortgage.
There are, however, different strategies you can use to pay off a mortgage early:
Pay an extra amount toward your principal along with your regular payment every month.
Pay an extra amount each year, such as from a work bonus or other annual windfall.
If you continue working after retirement age, you may want to allocate the required minimum distributions (RMDs) from a retirement account toward your mortgage.
Make large payments each year from an inherited IRA transferred from a deceased parent’s retirement account. Non-spouse heirs generally have 10 years to use up these funds. By withdrawing only a portion of the funds each year, the inherited IRA may continue to grow over the full 10-year period.
Pay off fully or a significant portion of the mortgage using other inherited funds from a deceased parent.
Not only does paying off the mortgage early shorten the life of the loan, but it also can save you tens of thousands of dollars in interest payments.
For some people, paying off a mortgage early may not be their best strategy. After all, if they have locked in a low, fixed interest rate on the loan for the entire term, their excess income may be better deployed to an investment portfolio. Over a 15-, 20- or 30-year period, regular contributions to an investment portfolio can earn even more than the equity built up in a home.
If you’re locked into a high-interest-rate mortgage, you may want to consider refinancing when rates are adjusted downward. This can help you allocate more money toward your principal. However, don’t be quick to refinance to a lower rate if you already have a low rate, as mortgages are structured to pay a higher percentage of interest on the front end of the loan. When possible, it’s best to refinance or pay extra principal in the early years of the loan rather than the later years – because refinancing could cause you to pay more interest in another front-loaded loan for another long term. Also, be aware that some mortgages have an early payoff penalty, generally during the early years of a refinance, so check before you pay it off early.
Another consideration is that mortgage interest is tax deductible, which may be a key tax saver for those in a high tax bracket.
It’s a good idea to pay off any high-interest debt you may owe, such as credit cards, auto, or student loans, before paying down your mortgage early. These debts may be costing you more money than you can save by paying off a low-interest mortgage. Once you’re debt-free, you can redeploy those payments toward your mortgage principal.
The decision to pay off a mortgage early depends on your situation and your priorities. Specifically, if you still need to build an emergency reserve fund, catch up on retirement savings, or pay down high-interest debt, you might be better off allocating money elsewhere. By the same token, if the investment markets are enjoying an upward trend and you have a low-interest mortgage, you may want to just let your money “ride” in the market so you have more available later – perhaps then you can pay off your mortgage before you retire.
Considerations For Paying Off a Mortgage Early
January 1, 2024 · Blog, Financial Planning, Uncategorized
⏱ 5 min read
For many, buying a home is the biggest asset they will ever own. However, you aren’t able to fully benefit from that asset until you pay off the mortgage; until then, it is technically a liability. The most common length of a mortgage loan is 30 years, but most people either sell their home, refinance their mortgage – or even pay it off before the end of that term.
What are the pros and cons of paying off a mortgage early? Obviously, you no longer have to make monthly payments, so money can be directed elsewhere. It is advisable to pay off your mortgage before you retire when most people live on a lower, fixed income. By having the mortgage paid off, that money can be redirected to other household expenses and/or provide higher discretionary income.
It should be noted that paying off your mortgage doesn’t provide relief from other routine, high-ticket home expenses such as property taxes, homeowners’ insurance, or regular maintenance. However, owning your home outright means it can’t be foreclosed on and taken from you. It also provides a large financial asset from which you can tap the equity or sell for a windfall.
While paying off your mortgage can provide security and peace of mind, you should consider all the factors before going down this path. For example, you may not have enough discretionary income to devote to making extra payments to your mortgage loan principal.
Usually, in the first 10 to 20 years of homeownership, buyers are juggling a multitude of financial obligations – raising a family, building an emergency fund, saving for college, taking annual vacations, and investing for retirement. That doesn’t always leave a lot of money left over for your mortgage.
There are, however, different strategies you can use to pay off a mortgage early:
Pay an extra amount toward your principal along with your regular payment every month.
Pay an extra amount each year, such as from a work bonus or other annual windfall.
If you continue working after retirement age, you may want to allocate the required minimum distributions (RMDs) from a retirement account toward your mortgage.
Make large payments each year from an inherited IRA transferred from a deceased parent’s retirement account. Non-spouse heirs generally have 10 years to use up these funds. By withdrawing only a portion of the funds each year, the inherited IRA may continue to grow over the full 10-year period.
Pay off fully or a significant portion of the mortgage using other inherited funds from a deceased parent.
Not only does paying off the mortgage early shorten the life of the loan, but it also can save you tens of thousands of dollars in interest payments.
For some people, paying off a mortgage early may not be their best strategy. After all, if they have locked in a low, fixed interest rate on the loan for the entire term, their excess income may be better deployed to an investment portfolio. Over a 15-, 20- or 30-year period, regular contributions to an investment portfolio can earn even more than the equity built up in a home.
If you’re locked into a high-interest-rate mortgage, you may want to consider refinancing when rates are adjusted downward. This can help you allocate more money toward your principal. However, don’t be quick to refinance to a lower rate if you already have a low rate, as mortgages are structured to pay a higher percentage of interest on the front end of the loan. When possible, it’s best to refinance or pay extra principal in the early years of the loan rather than the later years – because refinancing could cause you to pay more interest in another front-loaded loan for another long term. Also, be aware that some mortgages have an early payoff penalty, generally during the early years of a refinance, so check before you pay it off early.
Another consideration is that mortgage interest is tax deductible, which may be a key tax saver for those in a high tax bracket.
It’s a good idea to pay off any high-interest debt you may owe, such as credit cards, auto, or student loans, before paying down your mortgage early. These debts may be costing you more money than you can save by paying off a low-interest mortgage. Once you’re debt-free, you can redeploy those payments toward your mortgage principal.
The decision to pay off a mortgage early depends on your situation and your priorities. Specifically, if you still need to build an emergency reserve fund, catch up on retirement savings, or pay down high-interest debt, you might be better off allocating money elsewhere. By the same token, if the investment markets are enjoying an upward trend and you have a low-interest mortgage, you may want to just let your money “ride” in the market so you have more available later – perhaps then you can pay off your mortgage before you retire.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
A joint resolution providing for Congressional disapproval under Chapter 8 of Title 5, United States Code, of the rule submitted by the Bureau of Consumer Financial Protection relating to Small Business Lending Under the Equal Credit Opportunity Act (SJ Res 32) – This resolution was introduced on June 13 by Sen. John Kennedy (R-LA). It nullifies a rule issued by the Consumer Financial Protection Bureau (CFPB) that requires financial institutions to collect and report credit application data for small businesses to the CFPB. The bill passed in the House and the Senate on Dec. 1, but President Biden has threatened to veto the resolution because he believes it would reduce transparency and accountability in small business lending.
Caregiver Outreach and Program Enhancement (COPE) Act (HR 3581) – This bill supports various Veterans Administration initiatives: 1. Authorizes funding for the implementation, coordination, and enhancement of mental health counseling and treatment for participants (family caregivers of veterans) in the VA family caregiver program; 2. Authorizes the VA to contribute to local authorities to mitigate flooding risks on properties adjacent to VA medical facilities; 3. Requires an annual survey of police chiefs, facility emergency management leaders, facility directors, etc., for data regarding VA facility security; 4. Extends certain VA home loan fee rates through March 12, 2032. The legislation was introduced by Rep. Jennifer Kiggans (R-VA) on May 22. It passed in the House on Dec. 4 and is now in the Senate for review.
Housing our Military Veterans Effectively Act of 2023 (HR 3848) – This Act is designed to address issues related to homeless veterans. It increases the maximum per diem payments to authorized entities that provide transitional housing and services to homeless veterans. It also authorizes a maximum of 200 percent of the rate for veterans who live in rural areas, areas with high veteran suicide rates, and high rates of veteran homelessness. Furthermore, the bill authorizes the VA, through fiscal year 2024, to use certain funds to provide additional assistance to homeless veterans participating in the HUD-VA Supportive Housing program and to manage the use of VA land for homeless veterans to live and sleep. The legislation was introduced on June 6 by Rep. Lori Chavez-DeRemer (R-OR) and passed in the House on Dec. 5. Its fate currently rests with the Senate.
Support for Patients and Communities Reauthorization Act (HR 4531) – This bipartisan legislation reauthorizes (through the fiscal year 2028) grants, programs, and activities that address substance use. The provisions address data collection, education, and surveillance activities; support for substance use disorder (SUD) prevention, treatment, recovery, and trauma experienced by families of SUD patients; and student loan repayment and other resources for the SUD workforce. The legislation also modifies certain drug schedules of controlled substances and permanently requires that Medicaid cover medication-assisted treatment for eligible SUD patients. This bill was introduced by Rep. Brett Guthrie (R-KY) on July 11 and is co-sponsored by 37 Republicans and 27 Democrats. It passed in the House on Dec. 12 and is currently under consideration in the Senate.
Relaxing Small Business Accountability and Supporting Veteran Homelessness and Substance Abuse Disorders
January 1, 2024 · Blog, Congress at Work, Uncategorized
⏱ 3 min read
A joint resolution providing for Congressional disapproval under Chapter 8 of Title 5, United States Code, of the rule submitted by the Bureau of Consumer Financial Protection relating to Small Business Lending Under the Equal Credit Opportunity Act (SJ Res 32) – This resolution was introduced on June 13 by Sen. John Kennedy (R-LA). It nullifies a rule issued by the Consumer Financial Protection Bureau (CFPB) that requires financial institutions to collect and report credit application data for small businesses to the CFPB. The bill passed in the House and the Senate on Dec. 1, but President Biden has threatened to veto the resolution because he believes it would reduce transparency and accountability in small business lending.
Caregiver Outreach and Program Enhancement (COPE) Act (HR 3581) – This bill supports various Veterans Administration initiatives: 1. Authorizes funding for the implementation, coordination, and enhancement of mental health counseling and treatment for participants (family caregivers of veterans) in the VA family caregiver program; 2. Authorizes the VA to contribute to local authorities to mitigate flooding risks on properties adjacent to VA medical facilities; 3. Requires an annual survey of police chiefs, facility emergency management leaders, facility directors, etc., for data regarding VA facility security; 4. Extends certain VA home loan fee rates through March 12, 2032. The legislation was introduced by Rep. Jennifer Kiggans (R-VA) on May 22. It passed in the House on Dec. 4 and is now in the Senate for review.
Housing our Military Veterans Effectively Act of 2023 (HR 3848) – This Act is designed to address issues related to homeless veterans. It increases the maximum per diem payments to authorized entities that provide transitional housing and services to homeless veterans. It also authorizes a maximum of 200 percent of the rate for veterans who live in rural areas, areas with high veteran suicide rates, and high rates of veteran homelessness. Furthermore, the bill authorizes the VA, through fiscal year 2024, to use certain funds to provide additional assistance to homeless veterans participating in the HUD-VA Supportive Housing program and to manage the use of VA land for homeless veterans to live and sleep. The legislation was introduced on June 6 by Rep. Lori Chavez-DeRemer (R-OR) and passed in the House on Dec. 5. Its fate currently rests with the Senate.
Support for Patients and Communities Reauthorization Act (HR 4531) – This bipartisan legislation reauthorizes (through the fiscal year 2028) grants, programs, and activities that address substance use. The provisions address data collection, education, and surveillance activities; support for substance use disorder (SUD) prevention, treatment, recovery, and trauma experienced by families of SUD patients; and student loan repayment and other resources for the SUD workforce. The legislation also modifies certain drug schedules of controlled substances and permanently requires that Medicaid cover medication-assisted treatment for eligible SUD patients. This bill was introduced by Rep. Brett Guthrie (R-KY) on July 11 and is co-sponsored by 37 Republicans and 27 Democrats. It passed in the House on Dec. 12 and is currently under consideration in the Senate.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
In the world of accounting and auditing, there is a concept called materiality. The term materiality essentially means an amount that, if erroneously omitted or included, impacts the financials of a company to the point where they don’t tell the truth. One very basic example would be if a $1 million revenue small business made a mistake recording their accounts payable, and as a result, the business has $100,000 of expenses missing from their results. This would be material. If the same exact mistake happened in a multi-billion multinational company, it would not.
When it comes to materiality in accounting, there are many nuances that need to be considered when evaluating and determining what’s material and what’s not. One way to look at materiality from an accountant’s perspective is to determine how much a particular transaction (such as a purchase) or event (such as a lawsuit) will have on a company’s financial performance. Whether it’s an omission or a mistake in calculating and reporting such an event, the way an accountant evaluates and decides how to proceed with reporting the information (or not) can make a big difference in whether or not such information is material or immaterial.
Another way to look at whether information is material or immaterial is to determine if omitting (or through an accounting mistake) such information would mislead or change a person’s actions regarding the company (investing in, providing a loan to the company, etc.). If omitting the information would influence an outside party’s decision, it would be material. If including the mistake would not change an outside party’s decision regarding the company, it would be immaterial.
One consideration is the benchmark a company uses to determine if a transaction or event would trigger a materiality classification. For example, net profit, operating income, total assets/shareholder’s equity, gross profit, or gross revenue are commonly used. However, it’s important to keep in mind that operating income might not be the best metric if the business loses money, breaks even, or is modestly profitable.
When it comes to looking at net income and a loss, what matters is how big of a percentage the loss represents against the net income. If there’s a $10,000 loss of inventory (for example, due to a termite infestation of a special type of wood) at a furniture manufacturer that has annual sales of $100 million, it would be immaterial and not necessary to report it on the income statement. However, if this occurred at a start-up furniture factory with a net income of $50,000, it would be a 20 percent loss and would certainly make a material impact to investors, lenders, etc.
Documenting Decisions
The next step is for accountants to document their judgments and the reasons why they made each type of documentation. It’s a way for the internal financial managers or the auditor to determine what was done and why. One example looks at whether or not to depreciate or expense an item – for which the materiality depends on the item’s cost.
If an office desk costs $125, depreciating the office desk seems impractical and would likely be classified as a business expense during a company’s tax year. However, depending on the size of a business’ net income, a start-up may consider it material, but an established, publicly traded consumer staple corporation buying the same item would likely consider it immaterial.
Determining (im)materiality is often a judgment call by the financial experts within a company and the auditors who evaluate companies’ financial statements. With a consistent approach, businesses can make measured decisions for their internal and external audiences.
Defining Materiality in Accounting
January 1, 2024 · Accounting News, Blog, Uncategorized
⏱ 4 min read
In the world of accounting and auditing, there is a concept called materiality. The term materiality essentially means an amount that, if erroneously omitted or included, impacts the financials of a company to the point where they don’t tell the truth. One very basic example would be if a $1 million revenue small business made a mistake recording their accounts payable, and as a result, the business has $100,000 of expenses missing from their results. This would be material. If the same exact mistake happened in a multi-billion multinational company, it would not.
When it comes to materiality in accounting, there are many nuances that need to be considered when evaluating and determining what’s material and what’s not. One way to look at materiality from an accountant’s perspective is to determine how much a particular transaction (such as a purchase) or event (such as a lawsuit) will have on a company’s financial performance. Whether it’s an omission or a mistake in calculating and reporting such an event, the way an accountant evaluates and decides how to proceed with reporting the information (or not) can make a big difference in whether or not such information is material or immaterial.
Another way to look at whether information is material or immaterial is to determine if omitting (or through an accounting mistake) such information would mislead or change a person’s actions regarding the company (investing in, providing a loan to the company, etc.). If omitting the information would influence an outside party’s decision, it would be material. If including the mistake would not change an outside party’s decision regarding the company, it would be immaterial.
One consideration is the benchmark a company uses to determine if a transaction or event would trigger a materiality classification. For example, net profit, operating income, total assets/shareholder’s equity, gross profit, or gross revenue are commonly used. However, it’s important to keep in mind that operating income might not be the best metric if the business loses money, breaks even, or is modestly profitable.
When it comes to looking at net income and a loss, what matters is how big of a percentage the loss represents against the net income. If there’s a $10,000 loss of inventory (for example, due to a termite infestation of a special type of wood) at a furniture manufacturer that has annual sales of $100 million, it would be immaterial and not necessary to report it on the income statement. However, if this occurred at a start-up furniture factory with a net income of $50,000, it would be a 20 percent loss and would certainly make a material impact to investors, lenders, etc.
Documenting Decisions
The next step is for accountants to document their judgments and the reasons why they made each type of documentation. It’s a way for the internal financial managers or the auditor to determine what was done and why. One example looks at whether or not to depreciate or expense an item – for which the materiality depends on the item’s cost.
If an office desk costs $125, depreciating the office desk seems impractical and would likely be classified as a business expense during a company’s tax year. However, depending on the size of a business’ net income, a start-up may consider it material, but an established, publicly traded consumer staple corporation buying the same item would likely consider it immaterial.
Determining (im)materiality is often a judgment call by the financial experts within a company and the auditors who evaluate companies’ financial statements. With a consistent approach, businesses can make measured decisions for their internal and external audiences.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 When it comes to business operations and measuring performance, the optimal production scale a company can sustain is an important metric to measure. If a business’ capacity can’t be realized and sustained – or the bottlenecks can’t be identified and addressed in a timely manner – a business will likely stagnate and fail. Understanding more about capacity management can help businesses reduce the chances of dealing with sub-optimal performance.



 Email marketing remains the most powerful and effective tool, especially for its high ROI, reach, and engagement. It plays a significant role in business growth. However, more stringent measures are necessary due to evolving threats, hence the recent email deliverability requirements.
 Variance analysis is found by determining the difference between what was budgeted and what actually occurred. Additionally, when variances are added together, we get a better picture of how well a company is measuring its performance against expected metrics. It’s also important to be mindful that each metric is measured to determine what the actual cost is versus the industry’s standard cost.
 January has come and gone. You may or may not have stuck to your resolutions, but the good news is that February is here. Now is the perfect time to hunker down and get your monetary ducks in a row. Here are a few things to put on your agenda to get your financial house in order.
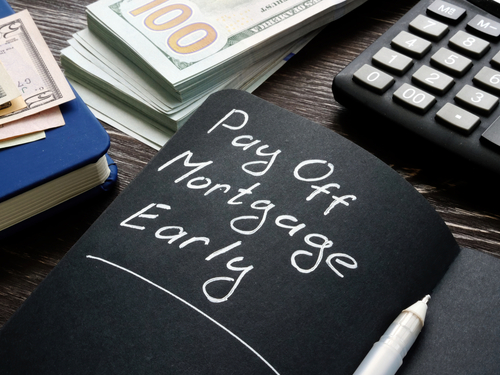 For many, buying a home is the biggest asset they will ever own. However, you aren’t able to fully benefit from that asset until you pay off the mortgage; until then, it is technically a liability. The most common length of a mortgage loan is 30 years, but most people either sell their home, refinance their mortgage – or even pay it off before the end of that term.
 A joint resolution providing for Congressional disapproval under Chapter 8 of Title 5, United States Code, of the rule submitted by the Bureau of Consumer Financial Protection relating to Small Business Lending Under the Equal Credit Opportunity Act (SJ Res 32) – This resolution was introduced on June 13 by Sen. John Kennedy (R-LA). It nullifies a rule issued by the Consumer Financial Protection Bureau (CFPB) that requires financial institutions to collect and report credit application data for small businesses to the CFPB. The bill passed in the House and the Senate on Dec. 1, but President Biden has threatened to veto the resolution because he believes it would reduce transparency and accountability in small business lending.
 In the world of accounting and auditing, there is a concept called materiality. The term materiality essentially means an amount that, if erroneously omitted or included, impacts the financials of a company to the point where they don’t tell the truth. One very basic example would be if a $1 million revenue small business made a mistake recording their accounts payable, and as a result, the business has $100,000 of expenses missing from their results. This would be material. If the same exact mistake happened in a multi-billion multinational company, it would not.